


Schedule FA is one of the most critical compliance requirements for Indian investors who hold foreign assets such as global stocks and ETFs.
A thorough understanding of the regulations and the required disclosures under Schedule FA is necessary to stay compliant and avoid additional scrutiny and penalties.
Table of contents
- What is Schedule FA?
- Who should file Schedule FA and report foreign assets?
- What foreign assets need to be disclosed in Schedule FA?
- What are the documents needed to file Schedule FA?
- What exchange rate should be used for reporting asset values in Schedule FA?
- Checklist for filing Schedule FA
- How Paasa helps with Schedule FA
What is Schedule FA?
Schedule FA (Foreign Assets) is a specific section within the Income Tax Return (ITR-2 and ITR-3 forms) where Resident Indians must disclose all assets they hold outside India.
The government uses this schedule to track ownership of global assets to ensure that money sent abroad is accounted for and not "hidden" from the tax net.
Who should file Schedule FA and report foreign assets?
The requirement to file Schedule FA depends entirely on your residential status in India, not your citizenship.
You MUST file Schedule FA if you meet these two conditions:
- You are a "Resident and Ordinarily Resident" (ROR) in India:
- If you qualify as an ROR for the relevant financial year, reporting is mandatory.
- Note: Non-Residents (NRIs) and "Resident but Not Ordinarily Residents" [(RNORs) are exempt] from filing Schedule FA, even if they hold foreign assets.
- You held a foreign asset "at any time" during the Calendar Year:
- This includes being the legal owner, a beneficial owner, or simply having signing authority (like being a signatory on a company's foreign bank account).
What foreign assets need to be disclosed in Schedule FA?
The scope of Schedule FA is extremely broad. The rule of thumb is: If it has financial value and is located outside India, you must declare it.
It does not matter if the asset is small, dormant, or generating zero income; disclosure is mandatory.
The schedule is divided into specific tables for different asset classes. Here is exactly what goes where:
1. Foreign Bank & Investment Accounts
- Depository Accounts (Table A1): All savings, current, and fixed deposit accounts in foreign banks. If you have old accounts you never declared, see how to declare old foreign bank accounts.
- Custodial Accounts (Table A2): Brokerage or investment accounts where you hold stocks, ETFs, or mutual funds.
- Required Details: Name of the bank/institution, account number, date of opening, peak balance during the year, and closing balance.
2. Equity & Debt Interests (Table A3)
- Direct Shares: Stocks of foreign companies you bought directly.
- RSUs & ESOPs: Vested shares of a foreign employer (e.g., if you work for a US tech giant). Even if you haven't sold them, you must report them once they vest. See the Schedule FA guide for RSU holders.
- Debt Interests: Foreign bonds, debentures, or notes.
- Required Details: Initial value of investment, peak value, and closing value.
3. Immovable Property (Table C)
- Any land, house, or commercial property located outside India.
- Required Details: Total investment at cost, address of the property, and any income derived from it (like rent).
4. Insurance & Annuities (Table A4)
- Foreign life insurance policies or annuity contracts that have a cash/surrender value.
- Required Details: The cash or surrender value of the contract and the total gross amount paid or credited under it during the year.
5. Signing Authority (Table E)
- You must disclose any account outside India where you have signing authority, even if you are not the owner of the funds (e.g., a corporate account for your employer or a family member's account).
6. Financial Interests & Other Capital Assets (Table B & D)
- Financial Interests (Table B): Any financial interest in an entity outside India, such as an interest in a foreign partnership or LLP, or a foreign company in which you hold shares or voting power.
- Other Capital Assets (Table D): Any other capital asset held abroad, like expensive jewelry, paintings, or vehicles.
7. Trusts & Other Income (Table F & G)
- Foreign Trusts (Table F): If you are a settlor, beneficiary, or trustee of a trust created under foreign law.
- Other Income (Table G): Any other income from sources outside India that is not reported in Tables A1 to F.
What are the documents needed to file Schedule FA?
To file Schedule FA, you don't actually need to upload documents to the Income Tax portal. You only need to manually enter specific details about your foreign assets into the tax forms.
Here is the checklist of mandatory information you need to gather for each asset category:
1. For Foreign Bank Accounts (Table A1)
- Bank Details: Name, address, and country code of the bank.
- Account Opening Date: The exact date you opened the account.
- Peak Balance: The highest balance in the account on any single day during the calendar year (in INR).
- Closing Balance: The balance as of December 31st.
- Gross Interest: Total interest credited to the account during the year.
2. For Foreign Stocks, RSUs, and ESOPs (Table A2 & A3)
- Entity Details: Name and address of the foreign company or the broker.
- Date of Investment: The date you acquired the shares.
- Initial Value: The total cost of acquisition (in INR).
- Peak Value: The highest market value of the holding reached during the calendar year.
- Closing Value: The market value of the holding as of December 31st.
- Gross Income: Total gross dividends earned or gross proceeds from any sales.
3. For Immovable Property (Table C)
- Property Details: Complete address of the property.
- Date of Purchase: The exact date of acquisition.
- Total Investment: The original cost of acquisition (Purchase Price).
- Income Derived: Any gross rent received from the property.
4. For Insurance & Annuities (Table A4)
- Policy Details: Name of the insurance company and address.
- Date of Contract: The start date of the policy.
- Total Gross Amount Paid/Credited: The total amount paid or credited to you under the contract during the calendar year.
- Cash/Surrender Value: The redeemable value of the policy as of December 31st.
5. General Details for All Assets
- Country Name & Code
- Nature of Ownership: Whether you are the legal owner, beneficial owner, or beneficiary. If you are both the legal owner and the beneficial owner, report yourself as the legal owner.
Important: Remember the Calendar Year rule. For your return for AY 2026-27 (FY 2025-26), you are looking at documents for the period of January 1, 2025, to December 31, 2025.
What exchange rate should be used for reporting asset values in Schedule FA?
Reporting foreign assets requires converting all foreign currency values (USD, GBP, EUR) into Indian Rupees (INR).
You must strictly use the Telegraphic Transfer Buying Rate (TTBR) of the State Bank of India (SBI) on the specific date. For where to find the rate and how it works, see SBI TTBR rate explained.
The specific date for the exchange rate depends on which column of Schedule FA you are filling.
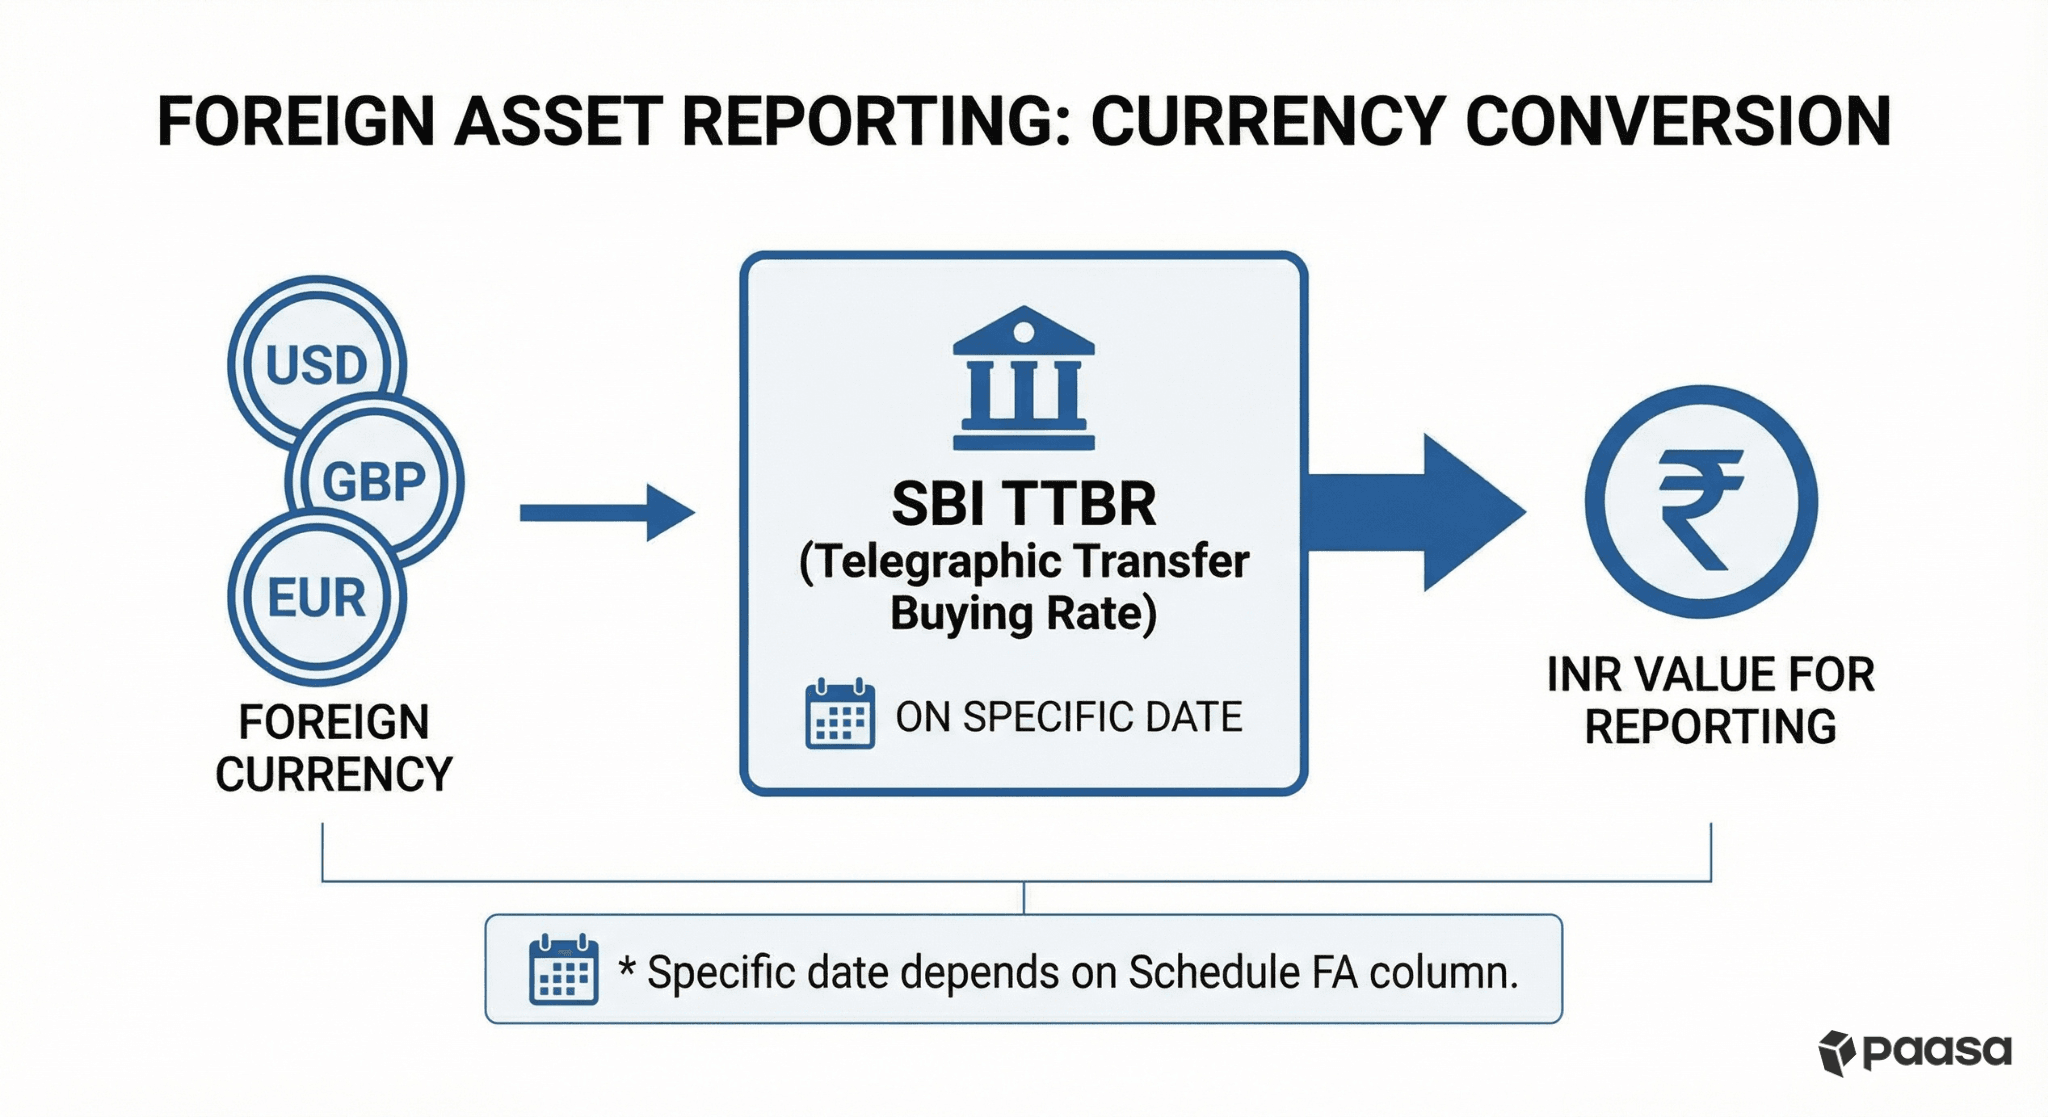
Here is the breakdown of which date's SBI TTBR you must use for each value:
Value to Report | Exchange Rate Date |
Initial Investment (Cost of Acquisition) | Use the SBI TTBR of the exact date of investment. |
Peak Value (Highest balance in the year) | Use the SBI TTBR of the exact date when the peak occurred. |
Foreign Sourced Income / Closing Balance | Use the SBI TTBR of December 31st (the last day of the calendar year). |
Pro tip: The Schedule FA instructions do not say which rate to use if the specific date (e.g., December 31st or the date of your peak balance) falls on a Sunday or a bank holiday. The common practice is to use the SBI TTBR of the immediately preceding working day.
Checklist for filing Schedule FA
To avoid common pitfalls and ensure you are compliant, run through this critical checklist before you submit.
Schedule FA follows the Calendar Year
Unlike the rest of your Income Tax Return which follows the Financial Year (April 1 to March 31), Schedule FA strictly follows the Calendar Year (January 1 to December 31).
For AY 2026-27, you must report assets held between January 1, 2025, and December 31, 2025.
You must report ALL foreign assets held during the year
You must file Schedule FA if you held a foreign asset or earned foreign income at any time during the relevant calendar year.
Even if your holding is "zero" right now, if you owned it for even a single second during the reporting period, it must be disclosed.
You need to use specific exchange rates for Schedule FA
The exchange rate calculations needed for Schedule FA are different from those needed for Form 67 (replaced by Form 44 from Tax Year 2026-27) and for calculating capital gains and dividend income.
Accuracy in Schedule FA is paramount as discrepancies can trigger scrutiny and penalties under the Black Money Act.
Important:
Failure to disclose an asset, even unintentionally, can lead to a penalty of ₹10 Lakhs for each year of non-disclosure under the Black Money Act and might result in prosecution.
Note: This penalty does not apply if the aggregate value of your foreign assets (other than immovable property) does not exceed ₹20 lakh. This threshold applies from October 1, 2024. You still have to disclose these assets in Schedule FA.
When in doubt, it is always safer to disclose.
Note: FAST-DS 2026 (Foreign Assets of Small Taxpayers - Disclosure Scheme) is a one-time scheme introduced by the Finance Act, 2026. Declarations can be filed from August 16, 2026, to December 31, 2026. For the full details, see FAST-DS 2026 explained. If you missed Schedule FA in earlier years, see how to fix missed Schedule FA years.
- Assets already taxed but not reported in Schedule FA: If your foreign assets were already offered to tax (or acquired while you were a non-resident) but not declared in Schedule FA, you can declare them by paying a flat fee of ₹1 lakh, as long as their aggregate value does not exceed ₹5 crore.
- Undisclosed foreign income or assets: If they were never offered to tax, you can declare them by paying 30% tax plus an additional amount equal to the tax, as long as their aggregate value does not exceed ₹1 crore.
A valid declaration gives you immunity from penalty and prosecution under the Black Money Act for the declared assets and income.
How Paasa helps with Schedule FA
Paasa is the platform used by global Indian Investors, NRIs, and family offices to diversify their wealth across global markets like US, UK, China, Singapore, Switzerland, and beyond.
Paasa’s tax advisory service offers complete filing support, from calculating correct values and exchange rates for reporting to ensuring that you are compliant with all regulations.
What type of documents does Paasa provide to file taxes?
At the end of the financial year, Paasa provides a ready-to-file tax package containing:
- Capital Gains Report: A clear breakdown of short-term vs. long-term capital gains, calculated using the holding-period rule for unlisted shares (more than 24 months is long term).
- Dividend & Interest Reports: Consolidated statements showing exactly how much income you earned and the tax withheld abroad, making it easy to fill Schedule FSI.
- Schedule FA Report: This is typically the hardest part of the ITR. We provide a report with the Peak Value and Closing Value of your assets in INR, calculated using the mandatory SBI TT Buying Rates, so you can simply copy-paste the numbers into your tax return.
We believe that global taxation should not come at the cost of your peace of mind. If you are investing in global equities and have doubts around taxation, FEMA, LRS, or compliance, feel free to reach out to our team.

