


If you are an Indian software professional working for a US company such as Microsoft, Google, or Amazon, a major part of your wealth is probably tied up in the form of RSUs.
You will eventually want to sell these RSUs either partially or fully for various reasons like diversification, funding a major purchase, etc.
But exactly how and when you sell your vested shares can have a significant impact on the total proceeds, or the net returns that you get.
This article provides a simple framework that you can follow to minimize your tax liabilities and get the most out of your RSU wealth.
It covers the mechanics of selling. If you are still deciding whether to sell or hold, start with what to do with vested RSUs in India.
Table of contents
- How RSUs are taxed
- The RSU selling framework
- Why employees sell their RSUs
- US estate tax considerations for Indian investors
- How Paasa helps
How RSUs are taxed
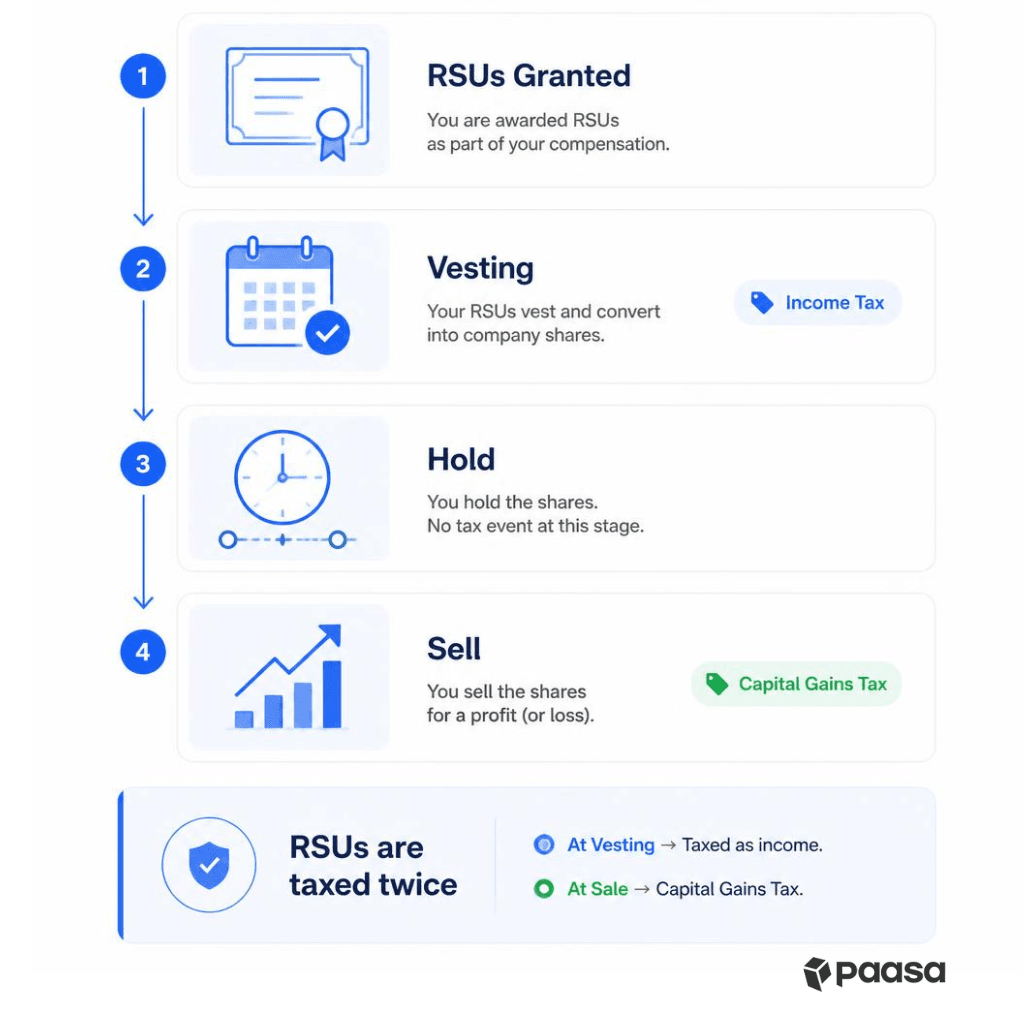
RSUs are taxed in two ways, once at vesting and once when you sell. Our guide on how foreign RSUs are taxed in India covers both stages in full.
When RSUs vest, they are taxed as income. The fair market value is added to your income and is taxed at the applicable income tax rate.
Once your RSUs have vested, they are treated as normal foreign shares and taxed accordingly at sale. If they distribute dividends while you hold them, those dividends are taxable in India at your slab rate, with the US-India DTAA setting the US withholding rate and allowing you to claim credit for it.
Tax at vesting
When RSUs vest, the fair market value of the shares is treated as your employment income.
Employers typically withhold taxes before the shares are delivered, which is why the number of shares received is often lower than the number that vested.
Importantly, this tax applies even if you do not sell the shares.
Capital gains tax after vesting
Once your RSUs vest and the shares land in your brokerage account, they are treated exactly like any other foreign-listed stock for capital gains purposes.
The capital gain or loss is calculated as: Sale value in rupees minus the rupee value of the shares at vesting
If the stock appreciates after vesting, you owe capital gains tax when you sell.
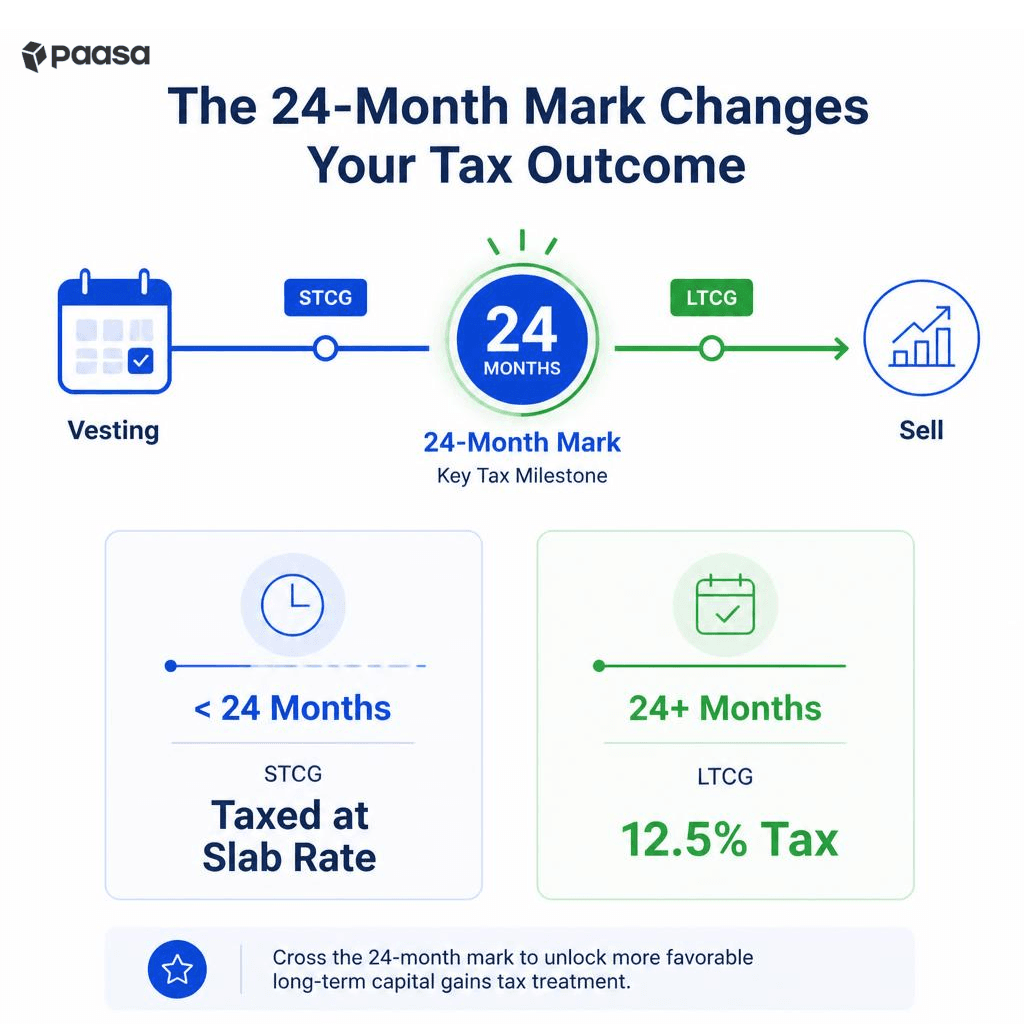
The rate of tax is decided based on your holding period.
| Holding period from vest date | Classification | Tax rate |
|---|---|---|
| 24 months or less | Short-term capital gains (STCG) | At your income slab rate |
| More than 24 months | Long-term capital gains (LTCG) | 12.5%, without indexation |
For RSU shares, the date of acquisition is the vest date.
To learn more, read our detailed guide on Capital Gains Tax on RSU Shares.
The RSU selling framework
The right approach depends on factors such as concentration risk, tax considerations, liquidity needs, and conviction in the company.
The following approaches illustrate some of the most common ways to manage vested RSUs, along with the risks associated with each.
1. Same-day sale
If a large part of your wealth is tied up in RSUs and you have decided to diversify, selling right after the shares vest is the simplest route.
Since the shares have barely moved since vesting, the capital gain, and the tax on it, will be close to zero.
Once you sell them, you are free to invest the money elsewhere.
Keep in mind: you still report the small gain or loss in your return, because the sale price will be slightly higher or lower than the value at vesting.
2. Hold for long-term capital gains
If you have decided to hold your company shares for now, holding them till they qualify for long term capital gains (LTCG) classification lowers the tax on any gain, though you carry the stock's price risk for that long.
In India, foreign shares held for more than 24 months qualify for the 12.5% long-term capital gains tax rate. If you sell them after holding for 24 months or less, your gains will be classified as short term capital gains (STCG) and taxed at your income tax slab rate.
Example
Here's how much difference the short term and long term classification can make in your net returns.
Suppose 100 Microsoft shares vest on April 1, 2024, at $400 per share.
The SBI TTBR on the last day of the preceding month was ₹83.00 and therefore your total acquisition cost was 100x400x83 = ₹33,20,000
We assume the selling price and the applicable SBI TTBR were the same on both dates, for ease of calculation.
Suppose the stock price was $480 on both selling dates and the SBI TTBR was ₹90.00.
Your total sale proceeds and the resulting capital gain are:
| Amount | Note | |
|---|---|---|
| Cost of acquisition (A) | ₹33,20,000 | 100 shares × $400 × ₹83.00, vest-day FMV already taxed as salary |
| Total sale proceeds | $48,000 | 100 shares × $480 |
| SBI TTBR | ₹90.0 per dollar | |
| Sale proceeds in INR (B) | ₹43,20,000 | $48,000 × ₹90.0 |
| Capital gain (B - A) | ₹10,00,000 | ₹43,20,000 − ₹33,20,000 |
Here's how your tax liability will look if you sell at 23 months and at 25 months:
Selling at 23 months
| Holding period | 23 months | April 1, 2024 to March 1, 2026 |
| Classification | STCG | 24 months or less |
| Tax at 30% | ₹3,00,000 | Applicable slab rate |
| Surcharge at 10% | ₹30,000 | Applicable if total income is ₹50L–₹1Cr |
| Health and education cess at 4% | ₹13,200 | On tax + surcharge |
| Total tax | ₹3,43,200 |
Selling at 25 months
| Holding period | 25 months | April 1, 2024 to May 1, 2026 |
| Classification | LTCG | More than 24 months |
| Tax at 12.5% rate | ₹1,25,000 | Applicable LTCG rate |
| Surcharge at 10% | ₹12,500 | Applicable if total income is ₹50L–₹1Cr |
| Health and education cess at 4% | ₹5,500 | On tax + surcharge |
| Total tax | ₹1,43,000 |
Holding the shares for more than 24 months reduced the tax liability from ₹3,43,200 (STCG) to ₹1,43,000 (LTCG), resulting in a tax saving of ₹2,00,200.
The saving applies only to the gain, and you earn it only if the share price holds while you wait.
3. Tax-loss harvesting
If your shares are trading below their vesting value, selling them generates a capital loss. A loss on shares held for 24 months or less can be set off against short-term or long-term gains, while a loss on shares held for more than 24 months can be set off only against long-term gains.
You can use this approach as part of a broader tax-planning strategy to lower your overall tax liability and offset some of the loss.
Risk: The loss becomes permanent once realized, and you will not benefit from any upside in the stock price. Decide based on your conviction and future outlook for the stock.
4. Staggered selling
If you hold a large position and do not want everything to depend on one day's price, you can sell it in parts on a fixed schedule, for example the same number of shares every month or every quarter.
A staggered sale spreads the exit across several prices. It also lets you choose which lots go first, since every vest is a separate lot with its own vesting date and cost.
- Order the lots: lots held for more than 24 months are taxed at 12.5%, lots vested most recently carry little gain, and lots trading below their vest value produce a loss. The lots in between, with a large gain and held for 24 months or less, are the costliest to sell.
- Fit it to your trading window: schedule each sale for a date when your company's trading window is open.
- Convert each sale separately: each sale is converted to rupees at the SBI TTBR on the last day of the month before that sale, so keep the contract note for every tranche.
- Plan the tax and the cash: gains from each tranche count towards the next advance tax instalment, and each sale's proceeds must be reinvested abroad, spent abroad on a permitted purpose or brought to India within 180 days under the FEMA 180-day rule.
Risk: You stay exposed to the stock for as long as the schedule runs, so a fall in the price hits the shares you have not sold yet. To set the schedule in advance as a written rule, read what to do with vested RSUs in India.
Why employees sell their RSUs
For many Indian professionals working at companies like Apple, Microsoft, Amazon, Google, and Nvidia, RSUs make up a significant portion of their total compensation. Over the years, as more RSUs vest and the stock appreciates, a large part of your wealth can become concentrated in your employer's stock.
This creates concentration risk, where a single company or sector can heavily influence your portfolio. Even if you hold RSUs from multiple tech companies, you're still exposed to the same sector risk.
A diversified portfolio reduces this risk by spreading your investments across many companies, so the impact of any single stock on your overall returns is limited.
Another major reason Indian professionals sell their RSUs is US estate tax.
US estate tax considerations for Indian investors
If you choose to hold vested RSUs for the long term, US estate tax is another factor to consider. Unlike capital gains tax, which applies when shares are sold, US estate tax applies to US-situs assets held at the time of death.
Shares of a US corporation are US-situs assets, regardless of where they are held or traded, so RSU shares in companies like Microsoft or Amazon fall squarely within scope. Non-residents who are not US citizens receive a flat unified credit of only $13,000 against the tax, which is what shelters the first $60,000 of estate value. Beyond that, the rate schedule runs progressively to 40%.
As a result, investors with significant holdings in US-situs shares should factor estate tax exposure into their long-term financial and succession planning.
For example, if you are an Indian resident who holds shares of US companies worth $500,000 at the time of death, the rate schedule produces a tentative tax of $155,800. After subtracting the $13,000 credit, the estate tax liability is $142,800.
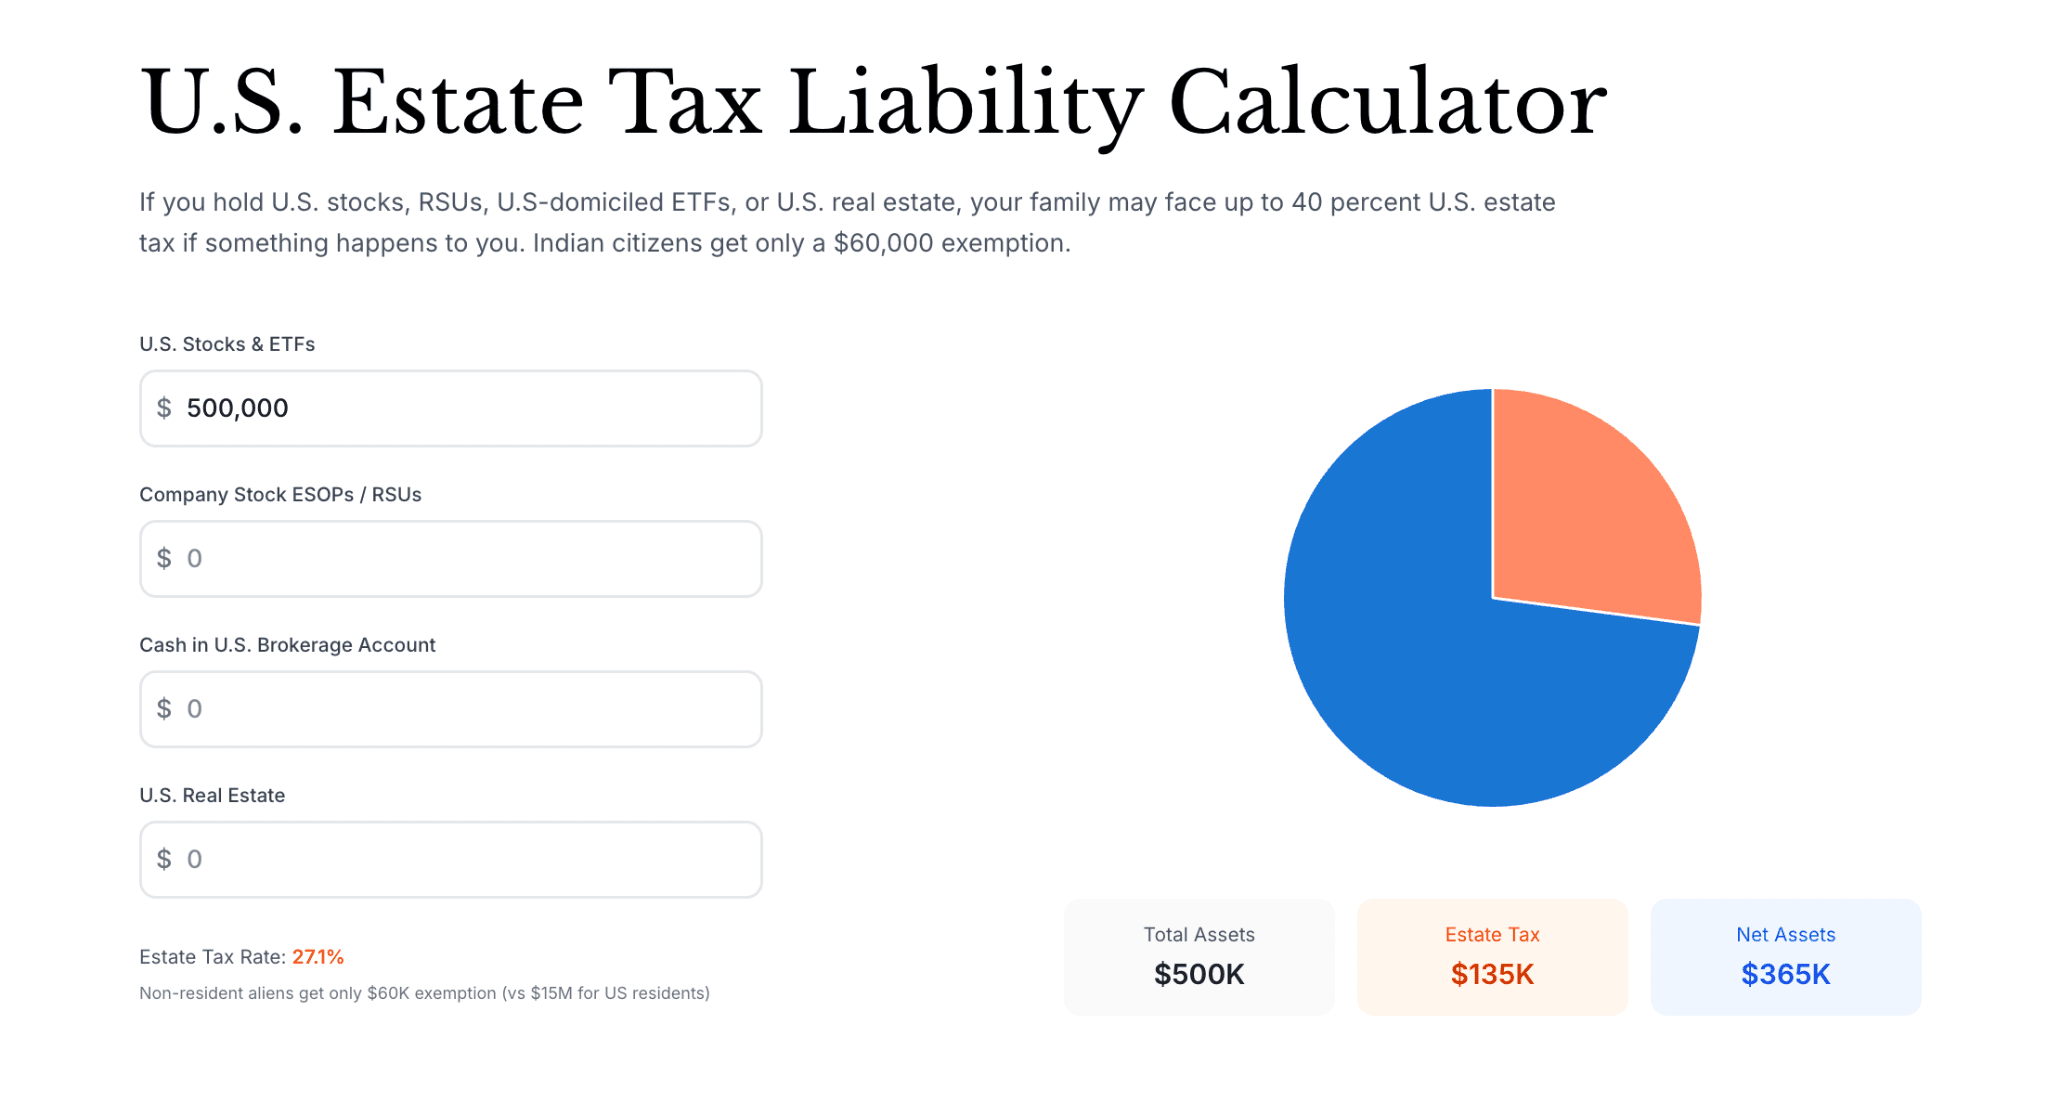
Use our Estate Tax Calculator to find your exact liability.
To learn about the US Estate Tax and how to protect your wealth from it, read our detailed guide on US Estate Tax for Indians.
How Paasa helps
Paasa is a global investing platform built for Indian and Asian investors, giving you direct access to stocks and ETFs across the US, UK, Europe and Asia from one account.
- Move your vested shares without selling: shares can be transferred in-kind from Fidelity, Morgan Stanley or Schwab, typically in 3 to 5 business days by ACATS from a brokerage account, with guidance for your specific broker.
- Diversify beyond one stock: reinvest across markets in 11 countries, including European-domiciled UCITS ETFs and mutual funds that are estate-tax safe for Indian residents.
- Tax reports for your Indian return: year-end reports for Schedule CG, Schedule FA and the foreign tax credit claim are sent automatically at the end of the financial year and can be shared with your CA.

