


If you are an Indian investor holding US stocks and ETFs (including RSUs), the US Estate Tax should be your top financial planning concern as it can wipe off up to 40% of your US-situs assets in the case of your death.
This blog talks about how the US Estate Tax is calculated and how you can find out your exact US Estate Tax liability using our Estate Tax Calculator.
Table of contents
- What goes into the calculation
- How is the estate tax calculated?
- Find your exact US estate tax liability
- What does your family need to do?
- How UCITS ETFs change the calculation
- More tools from Paasa
- About Paasa
What goes into the calculation
1. Who it applies to
Non-resident, non-citizens pay US estate tax on US-situs assets worth more than $60,000. Whether you count as a non-resident depends on your domicile, which we cover in our guide to US estate tax rules for Indians.
2. What counts
US-situs assets owned at the decedent’s death that are subject to US estate tax include:
- US real estate: Any land or property located in the US.
- Tangible personal property: Items physically located in the US, such as automobiles, furnishings, art, and jewelry. Note that cash and currency are considered tangible personal property and will be taxable if located in the United States (e.g., in a safe deposit box).
- US stocks: Shares of corporations organized in or under US law (e.g., Apple, Microsoft), even if the share certificates or brokerage account are held outside the US.
- Some US debt obligations: Debt issued by US companies or US persons whose interest does not qualify for the portfolio interest exemption. Most bonds held by investors do qualify, so they are not counted.
- Retirement plans: Qualified retirement plans (like 401(k)s) held in the United States.
- Business assets: Assets connected to a US trade or business, including bank accounts used for that business.
For estate tax purposes, the value of your US holdings is determined by their Fair Market Value (FMV) on the date of death.
3. What doesn't count
These assets are not treated as US-situs, so they are left out of the calculation (IRS):
- UCITS ETFs: Funds domiciled in Ireland or Luxembourg are not US-situs assets, even if they hold US stocks.
- Non-US stocks: Shares of companies not incorporated in the US.
- US bank deposits: Money in US bank accounts, as long as it is not connected with a US business.
How can I calculate the total estate tax liability?
The US estate tax is progressive, meaning the rate increases as the value of the estate rises. The rates range from 18% to 40%.
For non-residents, the calculation runs in two steps. The rate schedule is applied to the full value of your US-situs assets to arrive at a tentative tax. A flat unified credit of $13,000 is then subtracted from that figure.
Taxable estate | Tax on the lower amount | Rate on the excess |
$0 to $10,000 | $0 | 18% |
$10,000 to $20,000 | $1,800 | 20% |
$20,000 to $40,000 | $3,800 | 22% |
$40,000 to $60,000 | $8,200 | 24% |
$60,000 to $80,000 | $13,000 | 26% |
$80,000 to $100,000 | $18,200 | 28% |
$100,000 to $150,000 | $23,800 | 30% |
$150,000 to $250,000 | $38,800 | 32% |
$250,000 to $500,000 | $70,800 | 34% |
$500,000 to $750,000 | $155,800 | 37% |
$750,000 to $1,000,000 | $248,300 | 39% |
Over $1,000,000 | $345,800 | 40% |
Source: 26 U.S.C. 2001(c) for the rates and 26 U.S.C. 2102(b)(1) for the credit.
The $13,000 credit equals the tax on exactly $60,000, which is why $60,000 is the threshold. Above it, the credit stays fixed at $13,000 while the tax keeps climbing.
Example
Suppose you are an Indian businessperson with a globally diversified portfolio consisting of direct US stocks and US ETFs. The total value of your US assets (stocks and ETFs) is $800,000.
In case you pass away, the rate schedule is applied to the full $800,000:
| Tax Rate | Tax Due |
First $10,000 | 18% | $1,800 |
Next $10,000 | 20% | $2,000 |
Next $20,000 | 22% | $4,400 |
Next $20,000 | 24% | $4,800 |
Next $20,000 | 26% | $5,200 |
Next $20,000 | 28% | $5,600 |
Next $50,000 | 30% | $15,000 |
Next $100,000 | 32% | $32,000 |
Next $250,000 | 34% | $85,000 |
Next $250,000 | 37% | $92,500 |
Remaining $50,000 | 39% | $19,500 |
Tentative tax |
| $267,800 |
Less unified credit |
| -$13,000 |
Total Estate Tax Liability | Effective rate 31.9% | $254,800 |
The result: your heirs owe $254,800, an effective rate of 31.9%.
Here is the same calculation at other estate sizes.
US-situs estate | Tentative tax | Less credit | Tax due | Effective rate |
$60,000 | $13,000 | -$13,000 | $0 | 0% |
$100,000 | $23,800 | -$13,000 | $10,800 | 10.8% |
$250,000 | $70,800 | -$13,000 | $57,800 | 23.1% |
$800,000 | $267,800 | -$13,000 | $254,800 | 31.9% |
$2,000,000 | $745,800 | -$13,000 | $732,800 | 36.6% |
Note: Strictly, the rate schedule applies to your taxable estate, not the full value of your assets. For a non-resident, three terms matter:
- Gross estate: The total value of your US-situs assets at death.
- Taxable estate: Your gross estate minus allowed deductions, such as debts and funeral or administration expenses. This is the figure the tax is calculated on.
- Worldwide estate: Everything you own, in India and elsewhere. It is not taxed, but it limits your deductions. You can deduct only the share of your total debts and expenses that matches the share of your worldwide estate held in the US, and only if your worldwide estate is disclosed on the estate tax return (Section 2106).
For example, if your US assets make up 20% of your worldwide estate, only 20% of your total debts and expenses can be deducted. For most Indian investors, US holdings are a small part of their total wealth, so this deduction is small. The example above assumes no deductions, which makes it a close estimate of what your heirs would pay.
Example. Suppose you are an Indian resident with $500,000 of US stocks and a worldwide estate of $2,500,000, so the US share is 20%. Your total debts and funeral and administration expenses are $100,000.
Item | Amount |
Gross US estate | $500,000 |
Less deductible share of debts and expenses (20% of $100,000) | -$20,000 |
Taxable estate | $480,000 |
Tentative tax | $149,000 |
Less unified credit | -$13,000 |
Total estate tax | $136,000 |
Without the deduction, the tax would be $142,800, so the deduction saves $6,800.
The result: deductions help only in proportion to your US share, and only if the worldwide estate is disclosed on Form 706-NA.
Find your exact US estate tax liability
You can use Paasa’s Estate Tax calculator to instantly find out your total estate tax liability based on the value of your US assets.
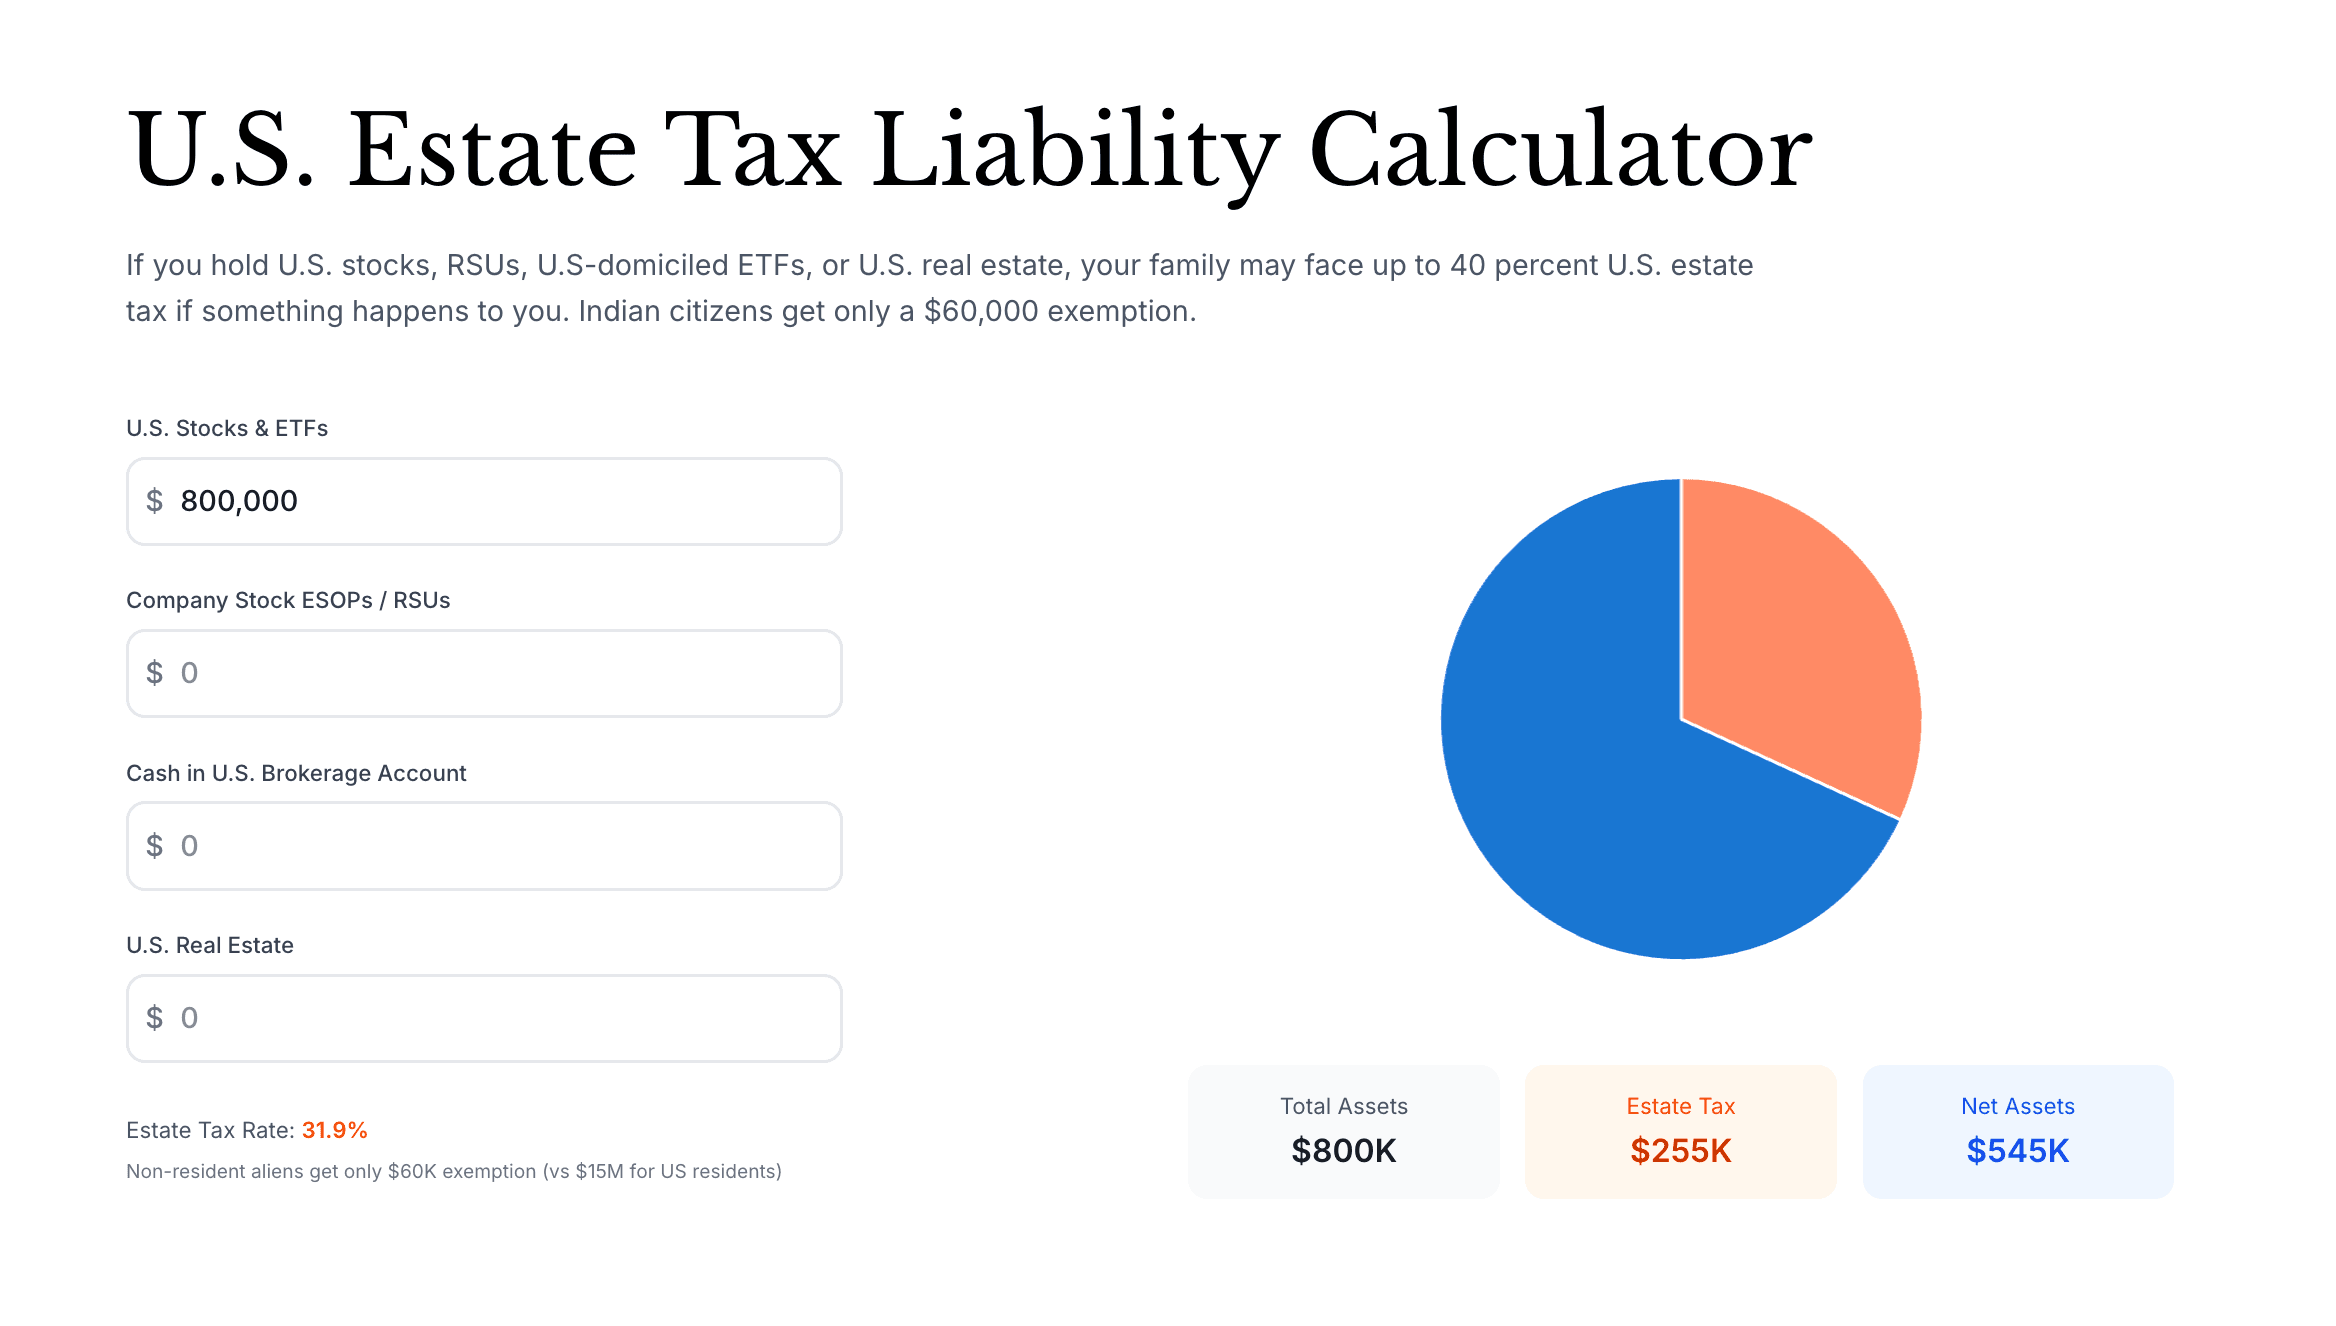
Simply put the value of your US assets here and our calculator will give you the exact tax liability and tax rate.
Use our estate tax calculator to find your exact liability.
What does your family need to do?
The executor of your estate must file Form 706-NA within 9 months of your death, with a 6-month extension to file available through Form 4768. US brokers usually release your assets to your heirs only after the IRS issues a transfer certificate.
Read what your heirs need to file for the full process.
How UCITS ETFs change the calculation
UCITS ETFs domiciled in Ireland or Luxembourg are not US-situs assets, so they are left out of the calculation. For example, $800,000 held in UCITS ETFs instead of US-listed ETFs adds $0 of US estate tax, against $254,800 in the example above.
Irish funds still pay 15% US withholding tax on US dividends inside the fund.
More tools from Paasa
- UCITS Screener: You can use Paasa’s UCITS Screener to discover and compare UCITS-compliant investment instruments.
- Brokerage Calculator: You can calculate your brokerage costs by Paasa’s Global Brokerage Calculator.
About Paasa
Paasa is a global investing platform for Indian residents and NRIs. It helps you work out and reduce your US estate tax exposure:
- Know your exposure: Use our estate tax calculator to see what your heirs would owe on your current US-situs holdings.
- Reduce it with UCITS ETFs: Invest in Ireland- and Luxembourg-domiciled UCITS ETFs that give you exposure to US companies but are not US-situs assets.
- Plan for your RSUs: Diversify concentrated RSU holdings with a plan for estate tax protection.

